

September Update
Headlines & Highlights
- U.S. rejects Tehran deal to open strait: Iran in late September offered to reopen the Strait of Hormuz and resume talks about the nation’s nuclear-weapons program in exchange for an end to U.S. actions that are hurting the Iranian economy. President Trump quickly rebuffed the offer, which called for the U.S. to lift both its naval blockade of Iran’s ports and sanctions on Iranian oil sales. Despite the rejection, Iran and the U.S. are reportedly using diplomatic channels to try to end the war in the Persian Gulf region, which has driven oil prices above $100 a barrel.
- Inflation measure cooler than expected: The latest update for the Federal Reserve’s preferred inflation gauge came in under expectations. The Personal Consumption Expenditures (PCE) Index for August showed that prices increased 3.4% for the preceding 12 months, which was less than the expected 3.7% rise as oil prices climbed sharply due to intensified fighting in the Middle East. Core PCE, which excludes food and energy, rose 3.0% over the 12 months, below the consensus forecast of 3.3%. Core PCE has been above the Fed’s 2% target for 66 consecutive months.
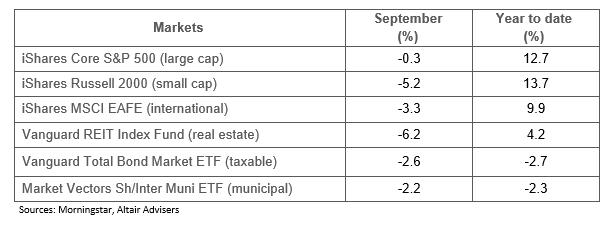
- Rising yields undercut stocks and bonds: Inflation worries accelerated a global bond selloff in September, pushing down bond prices and pushing up yields to multi-decade highs. This weighed heavily on stock and bond market returns – higher bond yields increase corporate borrowing costs and make new bonds more attractive to investors. The iShares ETF for the S&P 500 Index slipped 0.3% in September (+12.7% year to date), while the ETF for the small-cap Russell 2000 Index fell 5.2% (+13.7% YTD) and the Vanguard REIT Fund dropped 6.2% (+4.2% YTD) as both are more sensitive to interest-rate changes. A stronger U.S. dollar added to the downward pressure on international stocks. The Vanguard ETF for the U.S. bond market lost 2.6% in the month (-2.7% YTD) and Altair’s preferred municipal bond benchmark dipped 2.2% (-2.3% YTD).
Select Market Returns
Our Views
- When Iran and the U.S. are talking about ways to potentially end the war, the fighting tends to be subdued. The war has lasted longer than we originally expected, but most of it has been at a relatively low intensity. An increasing amount of oil is getting out of the Persian Gulf, limiting the war’s negative impact on the global economy.
- The lower-than-expected PCE inflation report for August and a weak September jobs report flipped the market’s view that the Fed would boost short-term interest rates at its October meeting – a 70+% likelihood has fallen to about 20%. Now the market bet is on a December move. We agree that the Fed needed to hike in September to maintain its credibility, and that inflation and employment trends should determine if more increases are needed.
- Higher yields on 10-year Treasurys are helping the Fed with its effort to reduce inflation by raising borrowing costs for businesses and consumers. This may limit the number of increases that the Fed needs to make to short-term rates. Benchmark 10-year Treasury yields have climbed to their highest level since 2002 – we believe they are now likely close to their peak.
- A strengthening economy is adding to the upward pressure on bond yields but it is not buckling even as money gets more expensive – much of the credit for this resilience goes to solid consumer spending and the expanding AI buildout. The Atlanta Fed currently estimates that U.S. GDP will grow at an annualized rate of 3.7% in the third quarter, markedly higher than the first two quarters of the year (2.5% and 2.2%, respectively).
- The U.S. stock story for 2026 continues to be driven by rising optimism about earnings growth given the economy’s durability. According to the financial data firm FactSet, third-quarter earnings for the S&P 500 are projected to be nearly 30% higher than in the same period last year. All sectors are showing positive growth, with tech and energy leading the way. The latest estimate from Strategas for small caps envisions 30+% earnings growth in 3Q.
The material shown is for informational purposes only. Past performance is not indicative of future performance, and all investments are subject to the risk of loss. Forward-looking statements are subject to numerous assumptions, risks, and uncertainties and actual results may differ materially from those anticipated in forward-looking statements. As a practical matter, no entity is able to accurately and consistently predict future market activities. Information herein incorporates Altair Advisers’ opinions as of the date of this publication, is subject to change without notice, and should not be considered as a solicitation to buy or sell any security. While efforts are made to ensure information contained herein is accurate, Altair Advisers cannot guarantee the accuracy of all such information presented. Material contained in this publication should not be construed as accounting, legal, or tax advice. See Altair Advisers’ Form ADV Part 2A and Form CRS at https://altairadvisers.com/disclosures/for additional information about Altair Advisers’ business practices and conflicts identified. All registered investment advisers are subject to the same fiduciary duty as Altair Advisers.
The material shown is for informational purposes only. Past performance is not indicative of future performance, and all investments are subject to the risk of loss. Forward-looking statements are subject to numerous assumptions, risks, and uncertainties and actual results may differ materially from those anticipated in forward-looking statements. As a practical matter, no entity is able to accurately and consistently predict future market activities. Information herein incorporates Altair Advisers’ opinions as of the date of this publication, is subject to change without notice, and should not be considered as a solicitation to buy or sell any security. While efforts are made to ensure information contained herein is accurate, Altair Advisers cannot guarantee the accuracy of all such information presented. Material contained in this publication should not be construed as accounting, legal, or tax advice. See Altair Advisers’ Form ADV Part 2A and Form CRS at https://altairadvisers.com/disclosures/ for additional information about Altair Advisers’ business practices and conflicts identified. All registered investment advisers are subject to the same fiduciary duty as Altair Advisers.